
Key Takeaways
- The monthly payment is not the same as the total cost of a loan; a longer term means more interest paid overall.
- Pre-approval from a lender does not lock you into that offer; it gives you a baseline to compare against dealer financing.
- A large down payment can reduce interest costs and lower the risk of owing more than the car is worth.
- Your credit score directly affects the interest rate a lender quotes, sometimes by thousands of dollars over the loan term.
- Dealer financing is not always the fastest or cheapest route; banks and credit unions are worth comparing first.
Why auto loan myths are expensive
Auto loan decisions tend to be made quickly, often at a dealership when attention is split between vehicle excitement and paperwork. That environment is where several persistent misconceptions take hold and lead borrowers to accept terms that cost more than necessary. The myths below are not obscure edge cases. They are the ones that consistently affect loan costs for everyday buyers.
This article provides general financial information for educational purposes and does not constitute personalized financial or lending advice. Consult a licensed financial professional for guidance specific to your situation.
Myth
The monthly payment is the number that matters most when comparing loan offers.
Fact
The monthly payment tells you cash flow, not total cost. Two loans with the same monthly payment can have very different total interest charges depending on the term length and rate.
A lender can make almost any vehicle seem affordable by stretching the repayment period. A 72-month loan at a higher rate may produce the same monthly payment as a 48-month loan at a lower rate, yet cost hundreds or thousands more in total interest. The figure worth comparing across offers is the annual percentage rate (APR), which captures the interest rate and most fees in a single number, alongside the total amount you will repay by the end of the term. See what the key numbers in a loan offer actually mean for a plain-language breakdown of each figure.
Myth
Getting pre-approved by a bank or credit union locks you into that loan.
Fact
Pre-approval is an offer, not a commitment. You can use it as a comparison point and walk away if dealer financing or another lender offers better terms.
Pre-approval tells you the rate and amount a lender is willing to extend before you step into a dealership. That information gives you negotiating leverage. If the dealer's financing department quotes a lower APR, you take that deal. If it quotes a higher one, you use your pre-approval. The process typically involves a hard credit inquiry, but multiple auto loan inquiries made within a short window (often 14 to 45 days, depending on the credit scoring model) generally count as a single inquiry. Gathering the right documents before you apply makes the process faster and more accurate.
Myth
You need perfect credit to get an auto loan.
Fact
Lenders approve borrowers across a wide range of credit scores, but borrowers with lower scores pay higher rates. The difference in total interest can be substantial.
Credit scores affect the interest rate a lender assigns, not always the approval decision itself. A borrower with a score in the mid-600s may qualify for a loan but receive a rate several percentage points above what a borrower with a 750 score receives. On a $25,000 loan over 60 months, even a 3-percentage-point rate difference can add over $2,000 in total interest. How credit scores shape auto loan rates walks through what score ranges typically mean in practice.
Myth
A small down payment is fine because you can always refinance later.
Fact
A low down payment increases the chance of going upside down on the loan, meaning you owe more than the car is worth, which can make refinancing harder, not easier.
New vehicles depreciate quickly, often losing a significant portion of their value in the first year. If your loan balance falls more slowly than the vehicle's market value drops, you end up with negative equity. That situation can complicate a sale, a trade-in, or a refinance application, because lenders are reluctant to refinance a loan that exceeds the vehicle's current worth. A down payment of at least 10 to 20 percent of the purchase price helps keep the loan balance closer to the vehicle's value. Why negative equity happens and how to reduce that risk covers the mechanics in detail.
Myth
Longer loan terms are always better because they lower your monthly payment.
Fact
Longer terms reduce the monthly payment but increase the total interest paid and extend the period of negative equity risk.
A 72-month or 84-month loan may feel manageable month to month, but the cumulative interest cost is higher than on a shorter term at the same rate. Longer terms also mean you are paying off the loan more slowly than the vehicle depreciates, which can leave you owing more than the car is worth for an extended period. Comparing short and long loan terms side by side puts the real cost difference in concrete numbers.
Myth
Paying off your auto loan early always saves money.
Fact
Early payoff can reduce interest costs, but some loan agreements include prepayment penalties that offset part of that savings.
Before making extra payments or paying off a balance in full ahead of schedule, check the loan agreement for a prepayment penalty clause. Some lenders charge a fee if the loan is paid off before a certain date, because early payoff eliminates the remaining interest income they expected. The fee structure varies: some are flat amounts, others are a percentage of the remaining balance. The full picture on early auto loan payoff covers both the potential savings and the things to check first.
What to do with this information
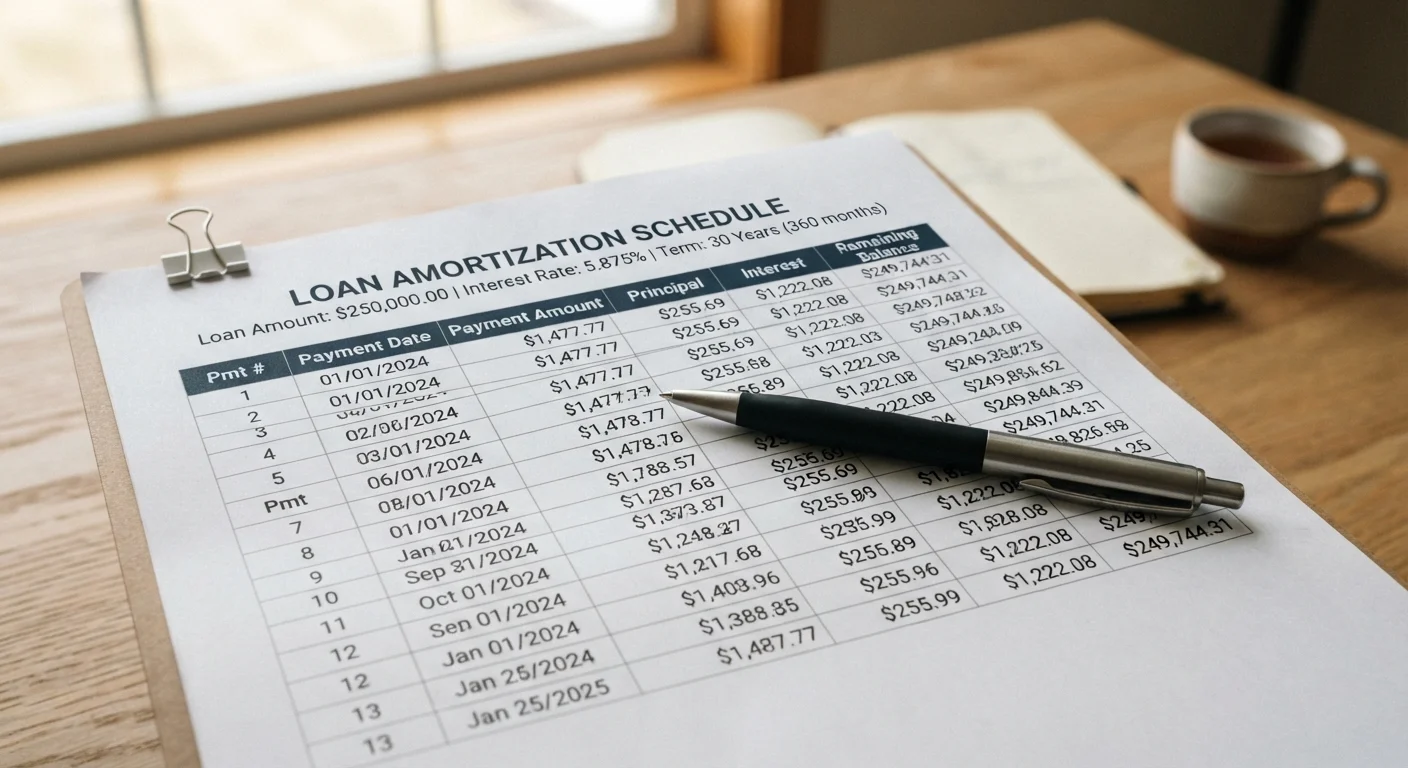
Each myth above points to a specific number or document worth reviewing before signing. Collect pre-approval offers from at least one bank or credit union before visiting a dealership. Pull up the loan's amortization schedule, which shows exactly how much of each payment goes to interest versus principal, and compare total repayment amounts across offers rather than monthly payments alone.
If you have an existing loan and believe you overpaid on the rate, refinancing may be worth evaluating, though timing and remaining balance affect whether it makes financial sense. For a complete walkthrough of each stage of the borrowing process, a first-timer's overview of auto financing covers the process from credit check to final payment.