
Key Takeaways
- Paying off a car loan early can reduce the total interest you pay over the life of the loan.
- Some lenders charge prepayment penalties that can offset or erase your interest savings.
- Early payoff may cause a temporary dip in your credit score due to changes in your credit mix.
- If your loan carries a low interest rate, putting extra money elsewhere may produce a better financial outcome.
- Always read your loan agreement before sending extra payments to confirm how the lender applies them.
Reduces total interest paid over the loan
Auto loans use simple interest calculated on the remaining principal. Every payment you make ahead of schedule shrinks the balance on which interest accrues, so the total cost of the loan falls.
Frees up monthly cash flow sooner
Once the loan is retired, the monthly payment amount becomes available for other expenses, savings, or debt reduction. For fixed-income borrowers, eliminating a recurring obligation can noticeably ease a budget.
Reduces debt-to-income ratio
Lenders use the debt-to-income ratio (DTI) when evaluating applications for mortgages or other credit. Removing an auto loan from your monthly obligations lowers your DTI, which can improve your position as a borrower.
Prepayment penalties can erase savings
Some loan agreements include a prepayment penalty, a fee charged when you pay off the balance ahead of schedule. Depending on the fee structure, the penalty can equal or exceed the interest you would have saved.
Potential temporary drop in credit score
Closing an installment account affects your credit mix and average account age, two factors in credit scoring models. The impact is usually modest and temporary, but borrowers planning to apply for new credit soon may want to weigh the timing.
Opportunity cost if your rate is low
If your auto loan carries a low interest rate, the money used for early payoff might generate a better return if directed toward high-yield savings, paying down higher-rate debt, or building an emergency fund.
Extra payments may not reduce principal automatically
Some lenders apply extra payments toward future scheduled payments rather than directly to principal. Without specifying in writing that the overpayment should reduce principal, you may not see the interest savings you expect.
Our Verdict
Paying off a car loan early makes the most financial sense when your interest rate is high, your loan has no prepayment penalty, and you have no higher-priority debt or savings gap to address first. It is less clear-cut when your rate is low, a penalty applies, or your emergency fund is thin.
Borrowers with a high-rate auto loan, no prepayment penalty clause, and a solid emergency fund who want to reduce total debt cost.
How early payoff works with a simple interest loan
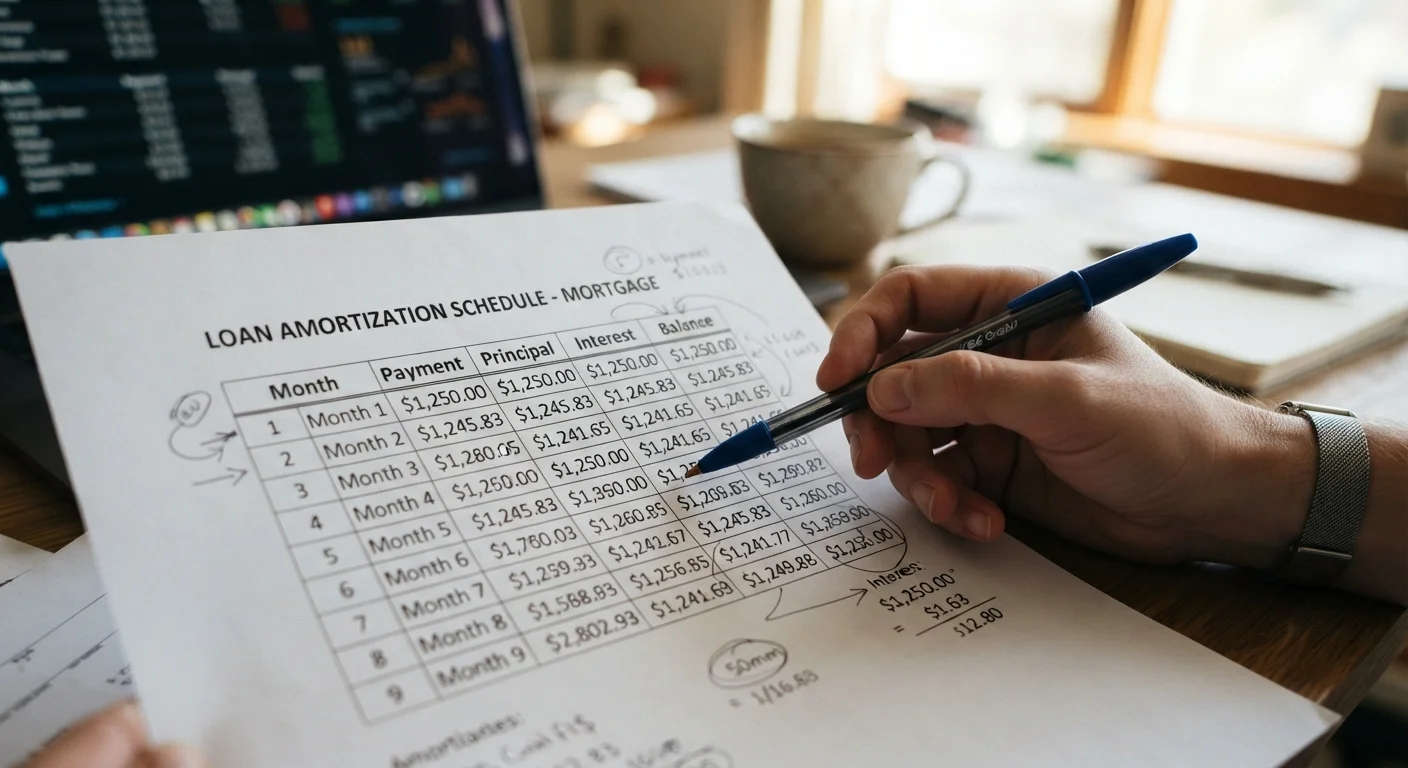
Most U.S. auto loans use a simple interest structure. Each month, the lender calculates interest based on your current outstanding principal. The earlier you reduce that balance, the less interest accumulates over the remaining term.
This is where amortization matters. In the early months of a loan, a larger portion of each payment covers interest rather than principal. As the balance falls, the interest share of each payment shrinks. Paying extra in the first half of a loan term has a larger effect on total interest than paying extra in the final months.
If you are new to how loan terms and rates interact, the first-timer's overview of auto financing covers the full picture from application to final payment.
The case for paying off early
Reduces total interest paid over the loan
Auto loans use simple interest calculated on the remaining principal. Every payment you make ahead of schedule shrinks the balance on which interest accrues, so the total cost of the loan falls.
Frees up monthly cash flow sooner
Once the loan is retired, the monthly payment amount becomes available for other expenses, savings, or debt reduction. For fixed-income borrowers, eliminating a recurring obligation can noticeably ease a budget.
Reduces debt-to-income ratio
Lenders use the debt-to-income ratio (DTI) when evaluating applications for mortgages or other credit. Removing an auto loan from your monthly obligations lowers your DTI, which can improve your position as a borrower.
The math tends to favor early payoff most clearly when your loan carries a rate above roughly 7 percent and no prepayment penalty applies. At higher rates, the interest saved over even a few months of early payoff can be meaningful on a loan of several thousand dollars.
The case against paying off early
Prepayment penalties can erase savings
Some loan agreements include a prepayment penalty, a fee charged when you pay off the balance ahead of schedule. Depending on the fee structure, the penalty can equal or exceed the interest you would have saved.
Potential temporary drop in credit score
Closing an installment account affects your credit mix and average account age, two factors in credit scoring models. The impact is usually modest and temporary, but borrowers planning to apply for new credit soon may want to weigh the timing.
Opportunity cost if your rate is low
If your auto loan carries a low interest rate, the money used for early payoff might generate a better return if directed toward high-yield savings, paying down higher-rate debt, or building an emergency fund.
Extra payments may not reduce principal automatically
Some lenders apply extra payments toward future scheduled payments rather than directly to principal. Without specifying in writing that the overpayment should reduce principal, you may not see the interest savings you expect.
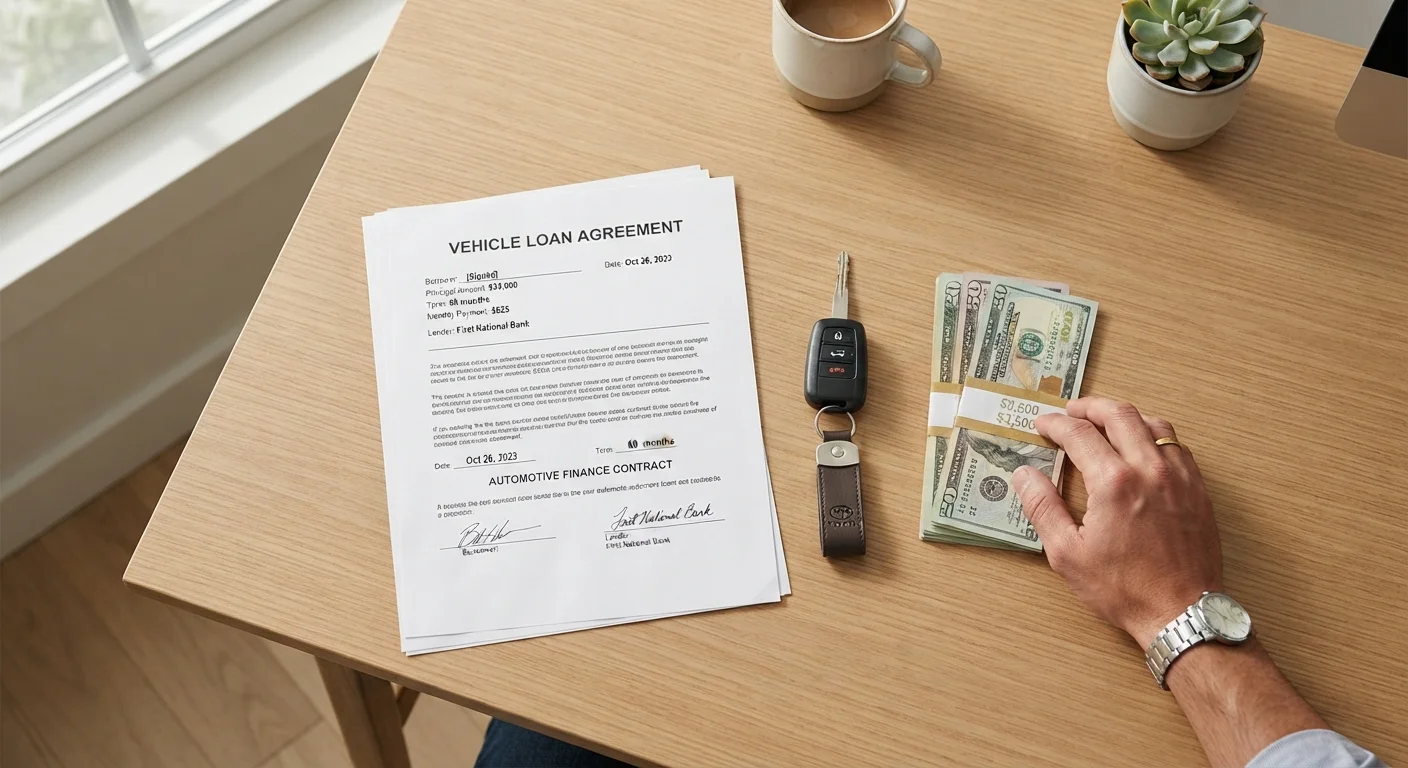
Before sending an extra payment, review your loan agreement for any prepayment clause. Understanding the numbers in a loan offer, including prepayment penalty terms, can prevent a costly surprise. Also confirm with your lender, in writing, that any overpayment will be applied to principal rather than to future scheduled installments.
How to confirm your prepayment terms
Your loan agreement should include a section on prepayment or early payoff. Look for language about penalties, fees, or the method used to calculate any remaining interest. If the document is unclear, contact your lender directly and ask for the payoff amount in writing. The payoff amount is often different from your current balance because it accounts for interest accrued to a specific date.
What to check before making extra payments
Four things are worth confirming before you commit extra money to your loan balance:
- Whether your agreement includes a prepayment penalty and how it is calculated.
- Whether your lender requires written instruction to apply extra payments to principal.
- Whether you have three to six months of living expenses in an accessible savings account. Depleting that reserve to pay off a low-rate loan leaves you exposed to unplanned costs.
- Whether any higher-rate debt (credit cards, personal loans) should take priority.
If your loan rate is low and you are weighing other options, refinancing your auto loan is another avenue worth examining, particularly if your credit profile has improved since you originally borrowed.
This article provides general financial information for educational purposes only. It is not personalized financial or legal advice. Loan terms, fees, and outcomes vary by lender and individual circumstances. Consult a licensed financial professional before making decisions about your own loan.