
Key Takeaways
- Filing too quickly or too slowly after an incident can both create problems with your claim.
- Your deductible amount directly affects whether filing a claim is financially worthwhile.
- Gaps in documentation are one of the most common reasons claims are delayed or disputed.
- Not all damage types are covered under every policy; reading your policy before an incident matters.
- A filed claim can affect your premium at renewal, even if the payout is small.
Why the steps before filing matter
Most drivers think about auto insurance at two points: when they buy a policy and when something goes wrong. The gap between those moments is where many costly errors occur. Understanding how the claims process works before you need it is the most practical way to protect yourself financially when an incident happens.
If you are newer to auto insurance or still comparing coverage options, a beginner's walkthrough of how auto policies work can help you build the foundation before going further.
Filing a claim without first calculating whether the payout exceeds the deductible and potential rate increase.
Why it happens: Many drivers assume filing is always the right move after any damage, without considering that the net financial gain may be minimal or negative.
Waiting too long to notify the insurer after an incident.
Why it happens: Drivers often want to assess damage on their own first, or hope the situation resolves without involving insurance.
Failing to document the scene thoroughly before moving or repairing the vehicle.
Why it happens: Stress and urgency at the scene lead drivers to skip photos, skip writing down details, or move the vehicle before gathering evidence.
Assuming all damage is covered without checking the policy's exclusions.
Why it happens: Policy language is dense, and many drivers do not read exclusions carefully until after a loss has occurred.
Admitting fault or making informal agreements at the scene.
Why it happens: Drivers want to be cooperative and may feel social pressure to apologize or settle quickly without insurer involvement.
Not keeping records of all communications with the insurer during the claims process.
Why it happens: The process can feel routine, and drivers assume verbal agreements or phone conversations are sufficient.
Documenting the scene correctly
One of the most preventable sources of claim problems is insufficient documentation. Insurers rely on evidence to assess what happened, and a sparse record puts the driver at a disadvantage during any dispute.
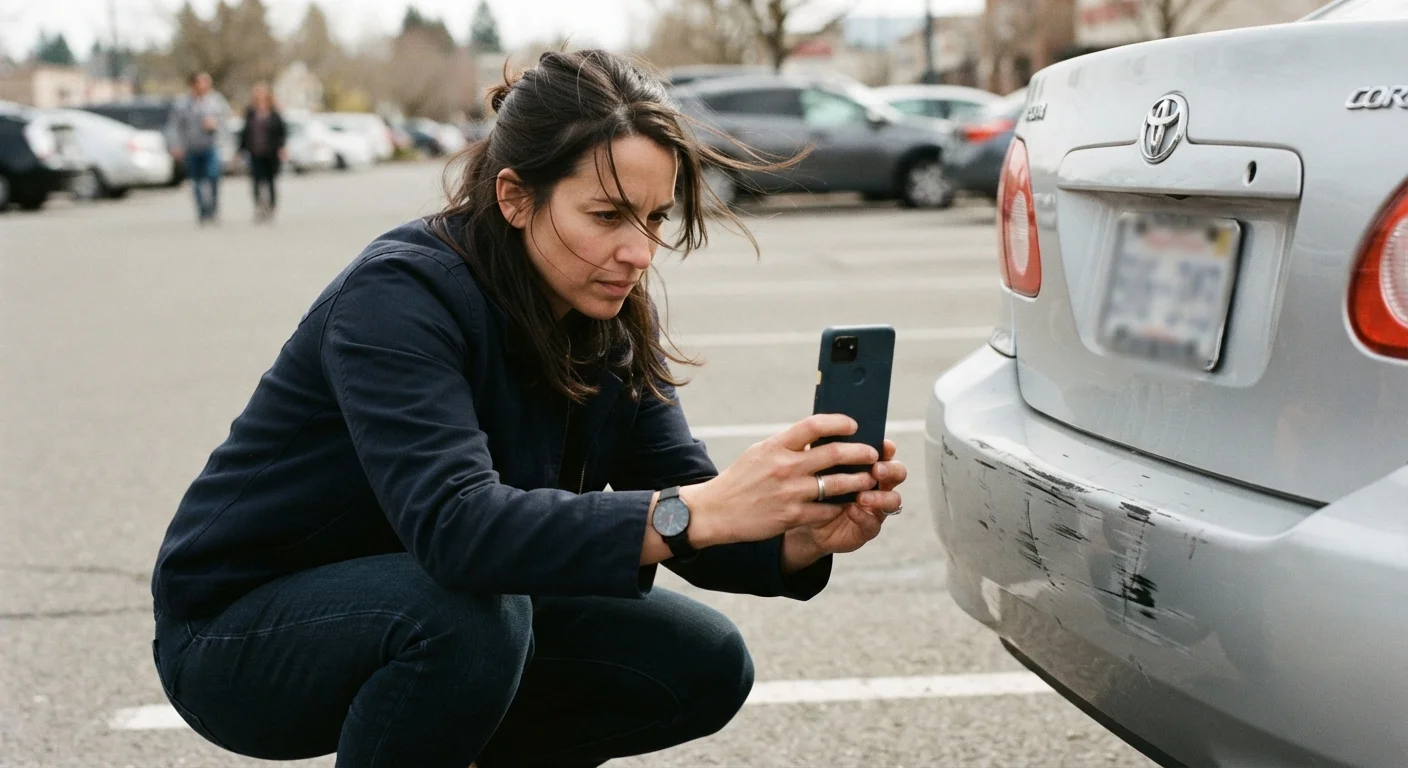
At the scene, photograph all visible damage from multiple angles, note the time and location, and record weather and road conditions. If there are witnesses, ask for their contact information. A police report, where available, adds an independent account that carries weight with adjusters.
Rate increases after filing a claim
Filing a claim, even a small one, can remain on your insurance record and affect your premium at renewal. The impact varies by insurer and state, but it is not uncommon for rates to rise after a first at-fault claim. Review what triggers rate changes so you are not caught off guard.
Weighing the financial decision to file
Not every incident warrants a claim. When repair costs are close to your deductible, filing may result in little or no net payout while still creating a record that affects your premium. This does not mean avoiding legitimate claims; it means making a deliberate calculation rather than filing automatically.
The math involves your deductible, the estimated repair cost, and the potential premium increase over the next renewal period. Drivers who carry a higher deductible for lower monthly premiums need to be especially aware of this tradeoff before filing for minor damage.
1 in 6
Insured drivers involved in an accident annually
According to the Insurance Research Council, approximately one in six insured drivers is involved in an accident each year in the United States.
40%+
Claims that involve a coverage dispute or documentation gap
Industry data from the Insurance Information Institute indicates that documentation issues and coverage misunderstandings are among the leading causes of claim delays.
This article is general information, not advice
Coverage rules, exclusions, reporting requirements, and claim procedures vary by insurer and by state. Nothing in this article constitutes personalized insurance, legal, or financial advice. For guidance specific to your policy and situation, consult a licensed insurance agent or adviser and read your actual policy documents.