
Key Takeaways
- An auto loan is a secured loan: the vehicle itself is collateral until you pay it off.
- Your credit score, income, and debt load all affect the interest rate a lender will offer.
- Longer loan terms lower monthly payments but increase total interest paid over the life of the loan.
- Getting pre-approved before visiting a dealership gives you a clearer budget and a stronger negotiating position.
- Reading the full loan agreement before signing is the single most important step in the process.
Start here
How auto loans work
Next
What lenders look at
Then
Loan terms and what they cost you
When you're ready
Getting pre-approved
Before you sign
Common mistakes to avoid
How auto loans work
An auto loan is a secured installment loan. You borrow a fixed sum to purchase a vehicle, then repay it in equal monthly payments over an agreed period. Because the loan is secured, the lender holds a lien on the vehicle until you make the final payment. If you stop paying, the lender can repossess the car.
Each monthly payment covers two things: a portion of the principal (the amount borrowed) and interest charged on the remaining balance. This structure is called amortization. Early in the loan, most of each payment goes toward interest. As the balance falls, more of each payment reduces principal.
For a broader look at how this applies to pre-owned vehicles, see used car financing explained. To compare how auto loans differ from longer-term vehicle financing, RV loan basics covers a different structure.
APR
Annual percentage rate. The yearly cost of borrowing expressed as a percentage, including the interest rate and any lender fees. A lower APR means less paid over the life of the loan.
Principal
The original amount of money borrowed, not counting interest. Each loan payment reduces the principal balance.
Loan term
The length of time you have to repay the loan, usually expressed in months. Common auto loan terms run from 24 to 84 months.
Pre-approval
A conditional offer from a lender stating how much they are willing to lend and at what rate, based on a review of your credit and income.
Debt-to-income ratio
The share of your gross monthly income that goes toward monthly debt payments. Lenders use this figure to assess whether you can afford additional debt.
Amortization
The process of paying off a loan through scheduled payments. Early payments cover mostly interest; later payments cover more principal.
What lenders look at
Lenders evaluate several factors when deciding whether to approve a loan and at what rate.
- Credit score: A higher score signals lower risk and typically results in a lower interest rate.
- Income and employment: Lenders want to see that you have stable income sufficient to cover monthly payments.
- Debt-to-income ratio: If a large portion of your income already goes toward existing debt, lenders may view additional borrowing as riskier.
- Down payment: A larger down payment reduces the loan amount and the lender's exposure if you default.
- Vehicle age and mileage: Older vehicles with high mileage may limit your financing options, since they lose value faster.
Lenders also look at the loan-to-value ratio, which compares the loan amount to the vehicle's market value. Borrowing more than the car is worth increases risk for both parties.
Check your credit report before you apply
You can request a free copy of your credit report from each of the three major bureaus through AnnualCreditReport.com. Reviewing it beforehand lets you spot errors and correct them before a lender sees them, which can improve the rate you are offered.
Loan terms and what they cost you
Loan term length has a direct effect on both your monthly payment and the total amount you pay.
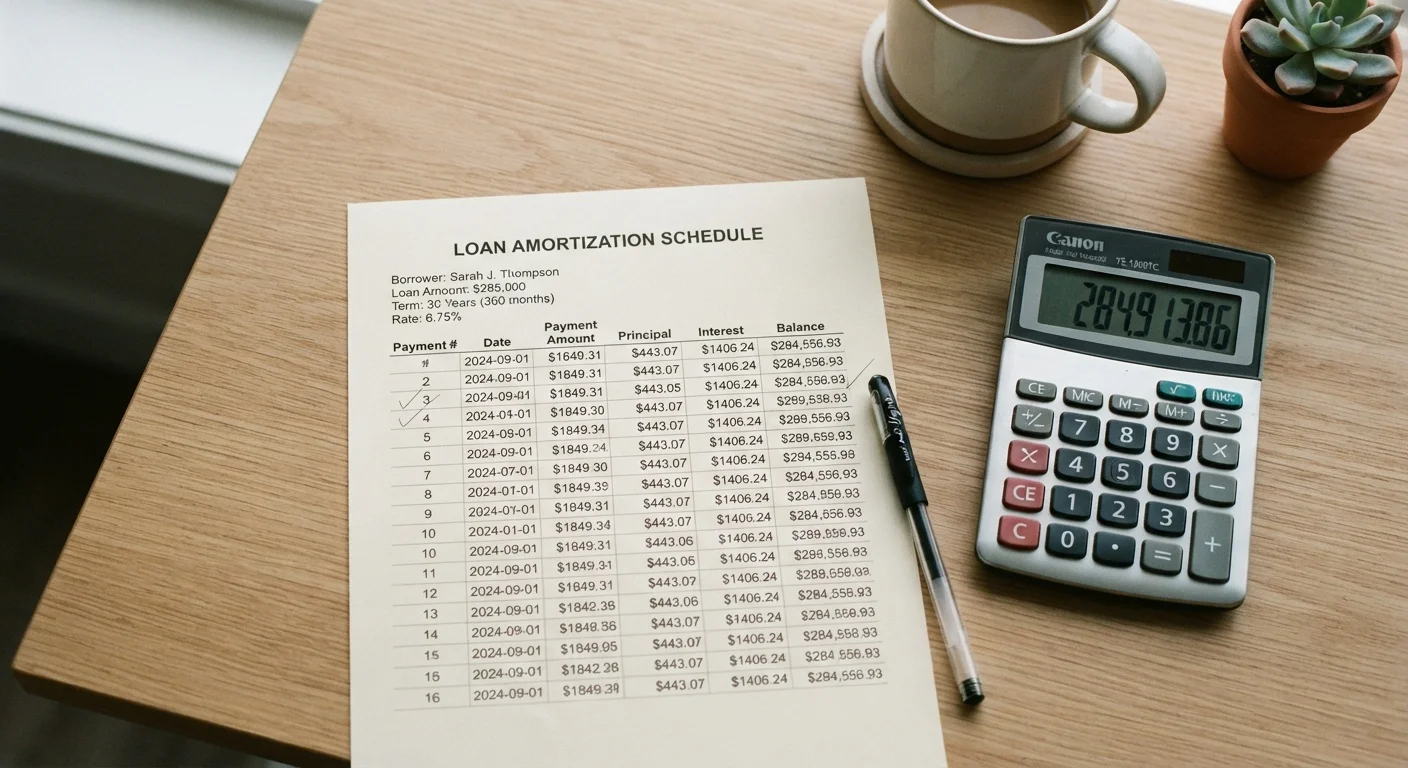
A 36-month loan carries higher monthly payments than a 72-month loan on the same principal, but you pay considerably less interest over the life of the 36-month loan. Stretching a loan to 72 or 84 months to reduce monthly payments is a trade-off that costs more in total interest and increases the time you spend underwater, meaning you owe more than the car is worth.
APR (annual percentage rate) determines how much interest accumulates. Even a difference of one or two percentage points compounds meaningfully over several years. Before accepting any loan offer, calculate the total repayment amount, not just the monthly figure.
Watch out for payment-focused negotiation
Dealers sometimes frame the entire conversation around monthly payments rather than total loan cost. A lower monthly payment stretched over a longer term can mean thousands more paid in interest. Always calculate the total amount you will repay before agreeing to any loan.
Getting pre-approved
Pre-approval means a lender has reviewed your credit and income and has issued a conditional offer stating the loan amount and rate they will extend. Going into a dealership with pre-approval gives you a concrete budget and a rate benchmark to compare against any dealer financing offer.
You can seek pre-approval from banks, credit unions, and online lenders. Applying to multiple lenders within a short window (typically 14 to 45 days) generally counts as a single credit inquiry for scoring purposes, so shopping around carries less risk to your credit than many borrowers expect.
Pre-approval is not a final commitment. The lender will verify vehicle details and finalize the loan once you choose a car. For a step-by-step walk through the full process, this first-timer's overview covers each stage in order.
This is general information, not financial advice
This article explains auto financing concepts for educational purposes. It is not personalized financial or legal advice. Loan terms, rates, and eligibility vary by lender and individual circumstance. Consult a licensed financial professional before making decisions specific to your situation.
Common mistakes to avoid
Several errors show up repeatedly among first-time borrowers.
- Skipping the credit check before applying, which means no time to dispute errors or pay down balances.
- Focusing only on monthly payment size rather than total loan cost.
- Accepting the first financing offer without comparing rates from at least one other source.
- Financing add-ons such as extended warranties or gap insurance into the loan without understanding their full cost over the term.
- Not reading the loan agreement in full before signing, including prepayment penalty clauses if any exist.
Once you understand the loan structure, insurance is the next piece of the puzzle. This beginner's walkthrough of auto insurance explains coverage types and what lenders typically require you to carry. The auto loans hub has additional resources for every stage of financing.
This article is for informational purposes only and does not constitute financial or legal advice. Loan terms and eligibility vary by lender and individual circumstances. Consult a licensed financial professional for guidance specific to your situation.