
Key Takeaways
- Used car loan rates are generally higher than new car rates because lenders view older vehicles as greater collateral risk.
- Your credit score is the single biggest factor lenders use to set your interest rate.
- A longer loan term lowers your monthly payment but increases the total interest you pay over time.
- Getting pre-approved by a bank or credit union before visiting a dealer gives you a concrete number to compare against dealer financing.
- Negative equity, where you owe more than the car is worth, is more likely with long loan terms and fast-depreciating vehicles.
- Reading the full loan agreement before signing, including fees and prepayment terms, is the clearest way to understand your actual cost.
Used car financing
Used car financing is a loan arrangement where a lender pays the seller for a vehicle and the buyer repays that amount, plus interest, in monthly installments over an agreed period. The vehicle itself typically serves as collateral, meaning the lender can repossess it if payments stop. Rates and terms on used car loans differ from new car loans because older vehicles carry more uncertainty for lenders.
The annual percentage rate (APR) on a used car loan includes both the interest rate and certain lender fees, making it a more complete cost measure than the stated interest rate alone.
How a used car loan is structured
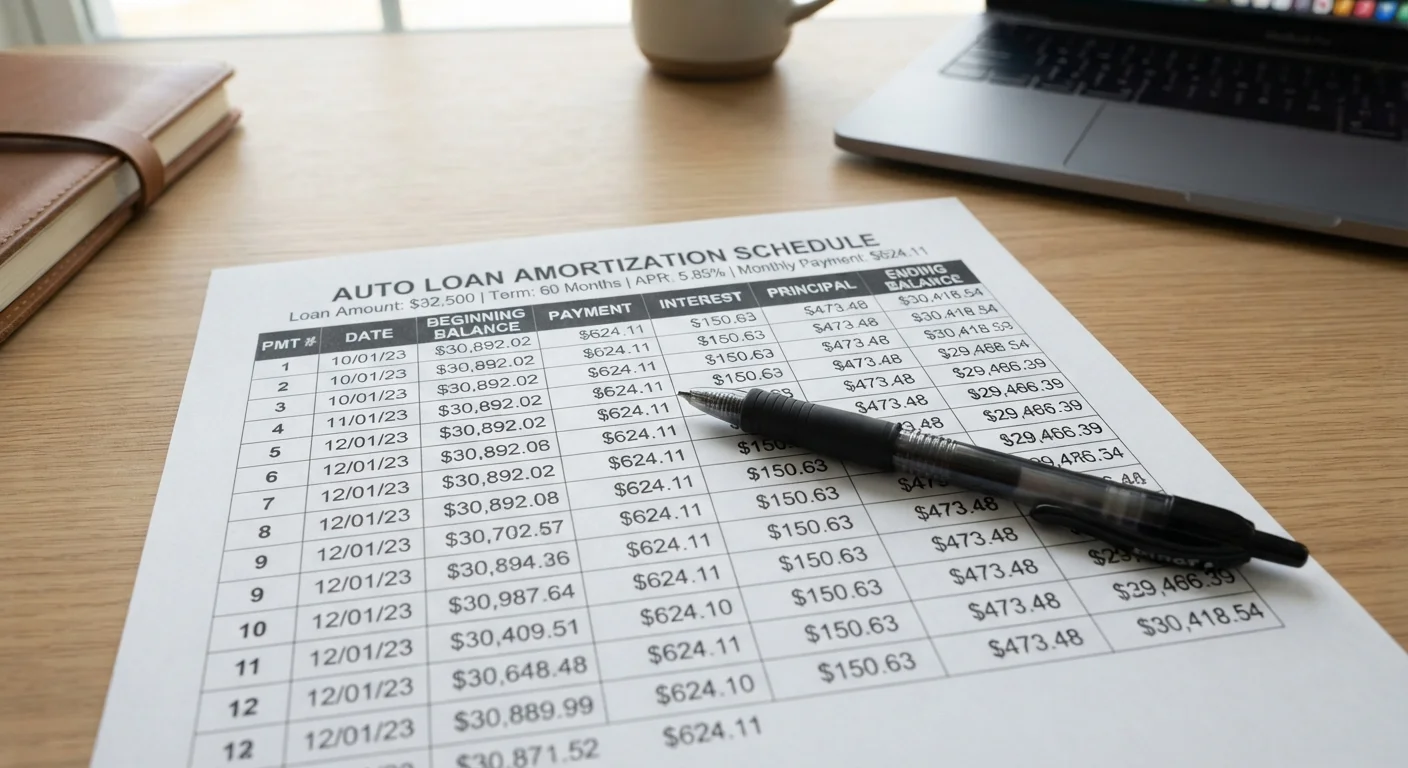
When you finance a used car, a lender pays the seller and you repay the lender in fixed monthly installments. Each payment covers two things: a portion of the principal (the amount borrowed) and interest (the lender's charge for the loan). Early payments are weighted more toward interest; as the balance falls, more of each payment goes to principal. This pattern is called amortization.
The total you pay depends on three variables: the loan amount, the interest rate (expressed as APR), and the loan term in months. Change any one of them and the others shift. A lower rate reduces total interest. A shorter term raises the monthly payment but cuts the overall cost. See how those trade-offs play out in our piece on short vs. long auto loan terms.
Used car loans also typically require the vehicle to meet certain age and mileage thresholds set by the lender. A car over 10 years old or with very high mileage may disqualify for standard financing or carry a higher rate, because the lender's collateral is worth less.
What drives your interest rate
Lenders set rates based on the risk they assign to you and to the vehicle. Credit score carries the most weight. A borrower with a score in the mid-700s will typically receive a meaningfully lower rate than one in the low-600s, and that gap compounds over a multi-year loan. Our article on how your credit score shapes your auto loan rate breaks down what those differences look like in dollar terms.
Other factors lenders weigh include your debt-to-income ratio (how much of your monthly income already goes to existing obligations), the loan-to-value ratio (the loan amount compared to the car's estimated market value), the vehicle's age and mileage, and the loan term itself. Longer terms add risk for the lender, which can push rates up slightly.
~2%
Typical rate gap: used vs. new car loans
Industry data from Experian's State of the Automotive Finance Market reports consistently show used car loan rates running roughly 2 percentage points higher than new car rates on average.
72 months
Most common used car loan term
Experian's automotive finance data shows 72-month terms have become the most frequently chosen option for used vehicle buyers in recent years.
Down payments affect the loan-to-value ratio directly. A larger down payment reduces the amount borrowed relative to the car's value, which can improve the rate a lender offers and lowers the chance of ending up with negative equity.
Choosing where to borrow
Borrowers have two main paths: direct lending through a bank, credit union, or online lender, or indirect financing arranged through the dealership. Both involve the same basic loan mechanics, but the process differs.
With direct lending, you apply before you shop and receive a pre-approval letter with a specific rate and loan ceiling. That gives you a concrete number to compare against whatever a dealer arranges. Credit unions in particular are worth contacting early; their rates are often lower than bank rates for borrowers who qualify for membership. The dealer financing vs. direct lending article walks through both paths in detail.
Dealer financing can be faster and sometimes includes manufacturer or dealer incentives, though those incentives apply mainly to new vehicles. On used cars, the dealer typically marks up the rate the underlying lender charges, keeping the difference as profit. Knowing your pre-approved rate prevents you from accepting a higher one without realizing it.
For a broader picture of the borrowing process from application to final payment, see auto financing from start to finish.
Reading and comparing loan offers
Two offers with similar monthly payments can have very different total costs. The monthly figure alone does not tell you what you are actually paying. Focus on APR, total amount financed, total interest over the life of the loan, loan term, and any fees (origination fees, prepayment penalties, or GAP insurance added to the loan balance).
GAP insurance (Guaranteed Asset Protection) covers the difference between what you owe and what the car is worth if it is totaled or stolen. It is sometimes included in financing packages at a markup. You can often purchase it separately for less, and it is worth comparing. Our article on reading an auto loan offer explains each line item in plain terms.
Before you finalize financing, it also helps to understand ownership costs beyond the sticker price, including insurance, registration, and maintenance, so the monthly loan payment fits into a realistic full budget. For full context on where financing fits in the purchase process, see the used car buying process, start to finish.
This article is for general informational purposes only and does not constitute financial or legal advice. Loan terms, rates, and eligibility vary by lender and individual circumstances. Consult a licensed financial professional before making borrowing decisions.